On 28 September 2026, the Central Board of Direct Taxes (CBDT) announced a major extension of the Tax Audit and Income Tax Return filing deadlines for AY 2026-27. CBDT subsequently issued Circular No. 07/2026, extending timelines for various audit reports and Income Tax Returns for specified taxpayers.
For covered taxpayers, the tax audit report deadline has been extended from 30 September 2026 to 21 October 2026, while the corresponding ITR filing deadline has been extended from 31 October 2026 to 21 November 2026.
The extension applies to Assessment Year 2026-27, corresponding to Previous Year 2025-26.
For businesses, companies, professionals, trusts and tax practitioners, the extension provides additional time to complete audits and return filings. However, it is important to understand exactly who is covered by the extension, which forms get additional time, and which deadlines remain unchanged.
For a detailed understanding of tax audit applicability, thresholds and Form 3CD reporting for AY 2026-27, see VIDUR’s Tax Audit AY 2026-27 Guide for CAs.
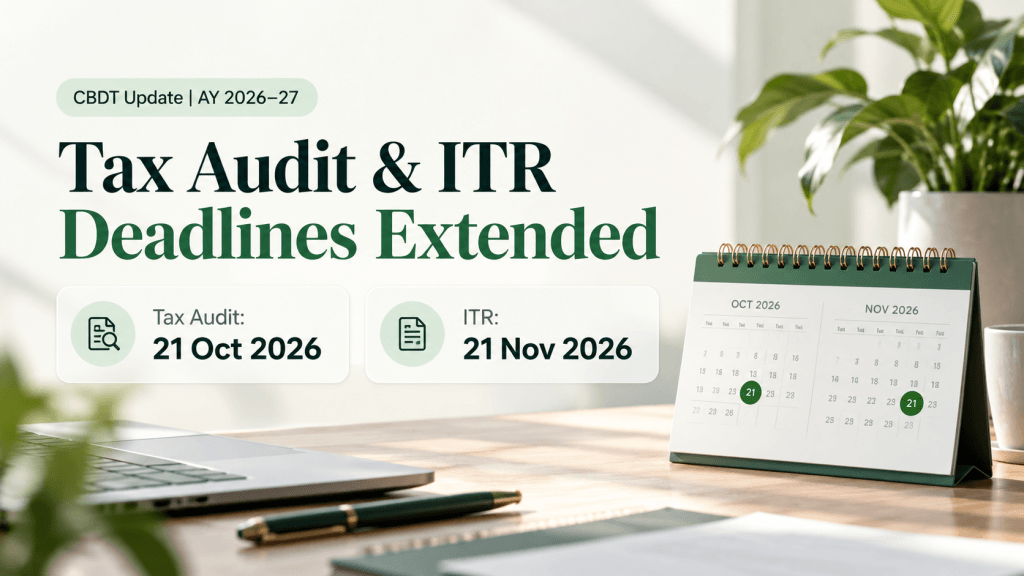
Revised Tax Audit and ITR Due Dates for AY 2026-27
The key changes announced by CBDT are:
| Compliance | Earlier Due Date | Extended Due Date |
|---|---|---|
| Audit Report for covered cases | 30 September 2026 | 21 October 2026 |
| Income Tax Return for covered cases | 31 October 2026 | 21 November 2026 |
The extension specifically applies to persons covered by Serial No. 2 of the Table below Explanation 2 to Section 139(1) of the Income-tax Act, 1961.
Who Is Affected by the Tax Audit and ITR Deadline Extension?
The extension is wider than only businesses and professionals liable for tax audit.
Broadly, the covered category includes:
- Companies: Companies whose return due date falls under the relevant 31 October category, except taxpayers separately covered by the transfer pricing deadline under Section 92E.
- Businesses and Professionals Subject to Tax Audit: Businesses and professionals whose accounts are required to be audited under the Income-tax Act or any other applicable law.
- Persons Covered by Section 44AB: Businesses generally become liable for tax audit where turnover exceeds Rs. 1 crore, subject to the enhanced Rs. 10 crore threshold where cash receipts and cash payments do not exceed the prescribed 5% limits. Professionals are generally covered where gross receipts exceed Rs. 50 lakh, subject to the specific provisions of the Act.
- Presumptive Taxation Cases Requiring Audit: Eligible taxpayers under Sections 44AD, 44ADA or 44AE may also become subject to audit where the applicable statutory conditions are triggered.
- Trusts and Non-Profit Institutions: Charitable or religious trusts and institutions whose accounts are required to be audited and whose audit reports in Form 10B or Form 10BB are linked to the specified date under the Income-tax Act.
- Partners of Audited Firms: Partners covered by the relevant due-date provision where the accounts of the firm are required to be audited.
- Other Persons Whose Accounts Require Audit: A person other than a company whose accounts are required to be audited under the Income-tax Act or under any other law for the time being in force.
The due-date category under Section 139(1) expressly covers companies, persons whose accounts are required to be audited, and specified partners of audited firms.
Detailed Breakdown of Extended Due Dates – Form-wise
The extension is not limited to Form 3CA, Form 3CB and Form 3CD. Various audit reports whose filing timeline is linked to the “specified date” under Section 44AB may also be impacted for eligible taxpayers.
| Form and Nature of Compliance | Original Due Date | New Extended Due Date | Applicability |
|---|---|---|---|
| Form 3CA / 3CB with Form 3CD – Tax Audit Report under Section 44AB | 30.09.2026 | 21.10.2026 | Businesses and professionals liable for tax audit and covered by the extension |
| Form 10B / 10BB – Audit Report for Trusts/Institutions | 30.09.2026 | 21.10.2026 | Applicable trusts and institutions required to furnish audit reports by the specified date |
| Form 29B / 29C – MAT / AMT Reports | 30.09.2026 | 21.10.2026 | Applicable taxpayers required to furnish reports for MAT or AMT computation |
| Form 10CCB / 10DA / 56F / 3CEA – Specified Reports and Certificates | 30.09.2026 | 21.10.2026 | Where the applicable statutory filing date is linked to the specified date under Section 44AB |
| Income Tax Return – Covered Audit Cases | 31.10.2026 | 21.11.2026 | Persons falling under the covered category of Section 139(1) |
| Form 10-IC / 10-ID – Concessional Corporate Tax Options | 31.10.2026 | 21.11.2026 | Where an eligible domestic company is exercising the relevant option and the form is required by the Section 139(1) due date |
| Form 10-IEA – Option relating to Section 115BAC | 31.10.2026 | 21.11.2026 | Applicable taxpayers carrying on business or profession whose relevant due date is linked to Section 139(1) |
Taxpayers should verify the governing provision and filing requirement for each form rather than assuming that every statutory form automatically receives an extension.
Why the One-Month Gap Matters
There is a legal connection between the tax audit report deadline and the ITR filing deadline.
The Explanation to Section 44AB defines the “specified date” for furnishing the tax audit report as the date one month prior to the due date for furnishing the return of income under Section 139(1).
Accordingly:
ITR Due Date: 21 November 2026
Audit Report Specified Date: 21 October 2026
The extension therefore preserves the statutory one-month interval between furnishing the audit report and filing the corresponding return of income.
What Is NOT Affected by the Extension?
It is equally important to understand which deadlines have not been extended.
Form 3CEB – Transfer Pricing Report
The deadline for furnishing the accountant’s report under Section 92E for international transactions or specified domestic transactions remains 31 October 2026, with the corresponding ITR due date remaining 30 November 2026, unless CBDT separately announces any change.
Taxpayers required to furnish a report under Section 92E fall under a separate return-filing category and should not automatically apply the 21 October and 21 November dates to their compliance.
Other Forms with Independent Timelines
Certain forms have separate statutory timelines and are not automatically affected merely because the audit or ITR deadline has been extended.
These include:
- Form 67 – Foreign Tax Credit: Under the current Rule 128 framework, Form 67 may generally be furnished on or before the end of the relevant assessment year where the return is furnished within the time permitted under Section 139(1) or Section 139(4). A separate rule applies to updated returns.
- Form 10BD / 10BE – Donation Statement and Certificate: These generally have a separate due date of 31 May following the relevant financial year.
- Form 10BA – Deduction under Section 80GG: This declaration follows its own filing requirements and should not be assumed to receive an extension merely because the audit or ITR deadline changes.
- Form 10-IA – Disability Certificate: This form also operates under separate requirements and is not automatically covered by the tax audit deadline extension.
Accordingly, taxpayers should check the statutory provision governing each form rather than applying the extended dates across all income-tax compliances.
Consequences of Missing the Extended Tax Audit Deadline
The additional time should be treated as a revised compliance deadline rather than an opportunity to postpone the audit until the last day.
For taxpayers liable for tax audit under Section 44AB, failure to get the accounts audited or furnish the prescribed audit report within the extended deadline may attract penalty proceedings under Section 271B.
The penalty can be the lower of:
- 0.5% of total sales, turnover or gross receipts, or
- Rs. 1,50,000
Reasonable Cause Exception
Section 273B provides relief from penalty under Section 271B where the taxpayer can establish that there was a reasonable cause for the failure.
Depending upon the facts and judicial precedents, circumstances considered in penalty proceedings may include events such as:
- Resignation of the tax auditor close to the filing deadline.
- Death or serious incapacity of the person responsible for accounts.
- Prolonged labour disputes, strikes or lockouts.
- Loss or destruction of accounting records because of fire, theft or natural calamity.
- Serious technical or system-related difficulties supported by appropriate evidence.
Whether a particular circumstance constitutes reasonable cause depends on the facts of the case and should not be assumed automatically.
What Should CAs and Taxpayers Do Now?
The extension gives taxpayers an additional 21 days, but it is advisable to use this period for review and reconciliation rather than delaying the compliance process.
For Chartered Accountants using VIDUR and other tax professionals, the additional period can be used to complete pending reconciliations, review Form 3CD disclosures, resolve client queries, verify statutory reports and ensure that the final return is consistent with the audited financial statements.
Particular attention should be given to:
- GST and turnover reconciliations.
- TDS and TCS reconciliation.
- AIS and Form 26AS differences.
- Section 43B and MSME disclosures.
- Loans, deposits and specified advances.
- Related-party transactions.
- Form 3CD reporting.
- Audit trail and supporting documentation.
Conclusion
The CBDT’s decision to extend the tax audit report deadline for AY 2026-27 to 21 October 2026 and the corresponding ITR filing deadline to 21 November 2026 provides significant relief to taxpayers and tax professionals.
However, the extension is not a blanket extension for every taxpayer or every income-tax form.
Taxpayers should first determine whether they fall within the category covered by Section 139(1) and then check whether the relevant audit report or statutory form is linked to the revised due date.
Businesses, companies, professionals, trusts and their advisors should use the additional time to complete audits accurately, resolve reconciliation differences and file well before the revised deadlines rather than waiting until the last day.